

Cashew—Expense Budget Tracker
by Dapper App Developer
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
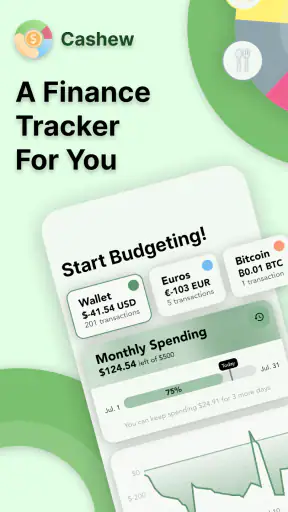
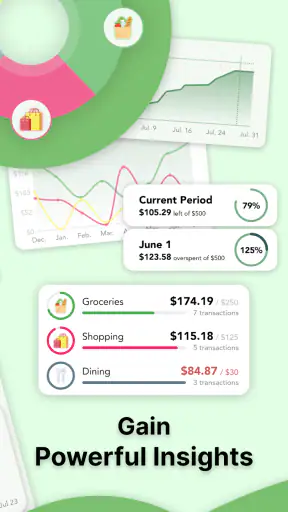
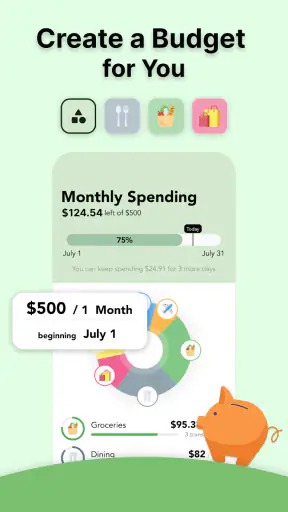
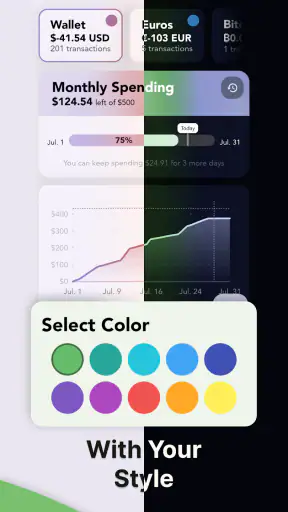
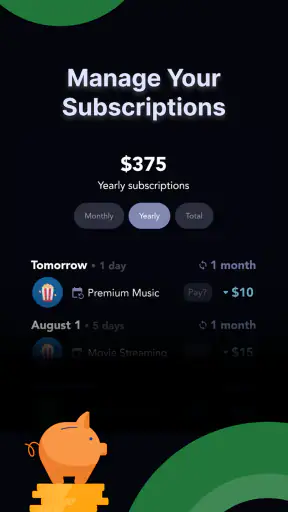
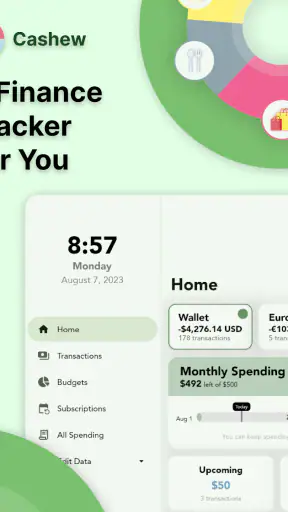
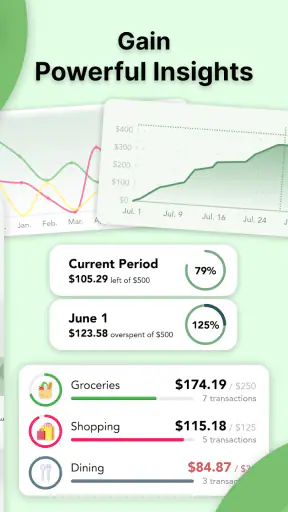
 Analysis by Getfullapps
Managing money sounds simple until small purchases start disappearing into the week. I installed Cashew—Expense Budget Tracker to see whether it could make that daily work easier without turning budgeting into another chore. My impression is that it is best understood as a focused expense tracker for people who want a clearer view of spending, rather than a complete replacement for every banking or financial-planning tool.
That distinction matters. Cashew is a free finance app from Dapper App Developer, with optional in-app purchases ranging from $1.49 to $19.99 per item. It is rated for Everyone, runs on Android 7.0 or later, and the current version is 6.6.11. Its 4.7 average from around 27 thousand ratings and more than 500 thousand installs suggest that the basic idea has found a substantial audience, but popularity alone does not tell you whether its approach fits your habits.
I approached it as a decision rather than a popularity contest: how quickly can I record an expense, how useful is the information afterward, and what kind of person will actually keep using it after the first enthusiastic week? Those are more useful questions than simply asking whether the app looks polished.
What I would decide before installing it
Before installing, I’d decide whether I’m willing to make expense entry part of my routine, because that choice matters more than setting up an elaborate budget. I’d also think about what I need to learn from my spending: a few useful categories can guide better decisions, while excessive detail can turn tracking into admin. With that expectation clear, it’s easier to judge how Cashew fits alongside the tools I already use.
Start with the kind of control you want
The first decision is whether you want awareness or automation. If your main goal is to notice where money goes, manually recording purchases can be surprisingly effective. The act of entering a coffee, transport fare, or household item creates a pause that a bank statement viewed once a month does not. Cashew suits that reflective style because its purpose is centered on tracking expenses and organizing a personal budget.
If you expect every transaction to appear automatically from your bank, you should choose a different category of tool. A banking app or an account-aggregation service may be more convenient for that particular job. Cashew makes more sense when you are willing to participate in the record-keeping, especially if you care about separating spending into meaningful categories instead of accepting whatever labels an institution assigns.
Think about the rhythm of your spending
Cashew is a stronger candidate for people with regular, understandable spending patterns. A student monitoring food and transport, a couple trying to control household purchases, or a freelancer watching irregular personal expenses can all benefit from a quick daily record. The app becomes less attractive if your finances involve many accounts, complicated business reimbursements, investments, debts, and shared transactions that need detailed reconciliation.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also think about the moment when an app must be used. A tracker that is excellent during a quiet Sunday review can still fail if recording a purchase feels slow while I am standing in a shop. Before committing to any budgeting system, I would test the complete cycle: enter a small purchase, assign it correctly, review the period, and adjust the budget. That short trial tells you more than a screenshot.
Decide how much structure you can maintain
Budgeting systems fail less often because of missing sophistication than because they demand too much attention. Cashew is most useful when you establish a small set of categories that you will actually use. I would avoid creating a separate category for every variation of a purchase. “Food,” “transport,” “home,” and “personal” may be more sustainable than a maze of labels that makes every entry a decision.
A practical test is whether you can record an expense without postponing it. If you regularly tell yourself that you will enter everything later, the app may become a weekend reconstruction exercise, and memory is not a reliable accounting system. In that situation, an automated alternative may be worth the trade-off even if it gives you less control over classification.
Where Cashew earns its place
Its clearest strength is focus. Instead of presenting itself as a broad financial institution, Cashew concentrates on the everyday question, “Where did my money go, and am I staying within the limits I set?” That narrow purpose can make a finance app easier to understand. I do not have to navigate investment screens or loan tools before dealing with a grocery purchase.
The free entry point also lowers the risk of trying it. You can begin with a simple routine rather than making a large commitment. Optional purchases are present, so I would review which extras are useful to me before paying, but the basic decision is straightforward: install it, test the recording habit, and judge the results from actual use.
Another advantage is the psychological feedback of manual tracking. When I enter an expense myself, I am more likely to remember the pattern behind it. A series of small convenience purchases can look different when each one is visible than when it is buried in a bank feed. That makes Cashew potentially valuable for someone who does not need financial automation but does need a stronger connection between spending and intention.
A realistic week with the app
Imagine a person trying to keep weekday spending under control. On Monday, they buy lunch and take public transport. On Tuesday, they add a household item and a snack. By Wednesday, the entries begin to show whether the problem is one large purchase or a repeated habit. The useful moment is not the individual entry; it is the review that follows. If the same category is consuming more of the planned amount than expected, the person can change behavior while the month is still in progress.
I would use Cashew in that situation at two separate times. I would record purchases soon after they happen, then review the totals at the end of the week. Separating those activities prevents constant analysis while still creating a regular correction point. The app is therefore not just a diary of past spending; it can become a small feedback loop between a purchase and the next decision.
Three practical habits that make it more useful
Record the reason, not only the amount. When a category is unexpectedly high, I want to know whether the cause was a planned event, an emergency, or a repeated impulse. Keeping categories meaningful makes later reviews more actionable than simply collecting numbers.
Use a short weekly reset. A weekly review is long enough to reveal patterns but short enough to catch mistakes. I would check uncategorized or questionable entries, compare spending with the budget, and decide on one adjustment for the following week.
Separate fixed commitments from flexible choices. Treating rent, subscriptions, groceries, and spontaneous purchases as one undifferentiated total hides where change is possible. A budget is more useful when it distinguishes obligations from areas where I can realistically cut back.
These habits are not flashy features, but they are where a tracker becomes useful in real life. The app can show a record; the value comes from building a routine that turns that record into a decision.
What may slow you down
Manual entry is both the app’s useful discipline and its main friction. Every system that depends on user input has a failure point: forgotten purchases, inconsistent categories, and entries made days later. Cashew cannot remove that responsibility. If you make many transactions throughout the day, the repeated taps may eventually feel like work.
There is also a learning cost in deciding how your budget should be organized. New users often expect the app to tell them the perfect categories and limits. In practice, a personal budget reflects priorities that the app cannot choose for you. A category can be technically accurate yet still unhelpful if it does not match the way you make decisions.
The presence of optional purchases is another consideration. The app is free to start, but anyone who prefers a completely paid-once or entirely open-source approach may want to compare that model with alternatives before investing time in setup. I would not pay for extras simply because they exist; I would first confirm that the daily tracking habit is already working.
How it compares with other ways to manage money
I’d compare Cashew with alternatives by asking what I want the tool to do: reduce data entry, offer flexible analysis, or make spending limits feel tangible. Each approach solves a different problem, and combining tools can sometimes be more practical than expecting one app to handle everything. That trade-off is worth keeping in mind when deciding whether a focused expense tracker earns a lasting place in my routine.
Compared with a banking app
A banking app usually wins for convenience and account visibility. It is the natural choice when the priority is checking balances, moving money, or seeing transactions tied directly to an account. Cashew wins when the priority is intentional categorization and a personal budgeting routine that is not limited to one institution.
The trade-off is clear: the bank app may reduce data entry, while Cashew may encourage more awareness. I would choose Cashew alongside a banking app if I wanted deliberate budgeting, not instead of the bank app for account management. That combination does require accepting some duplication, since the tracker and the bank may both contain a record of the same purchase.
Compared with a spreadsheet
A spreadsheet offers almost unlimited customization. Someone comfortable with formulas can build detailed reports, split shared costs, or design unusual categories. It can be the better choice for a household with complex rules or a freelancer who needs a highly tailored system.
Cashew is more appealing when the barrier is effort rather than flexibility. A spreadsheet can become powerful, but it can also become a project. A dedicated tracker keeps the focus on entering and reviewing expenses rather than maintaining formulas and layouts. I would choose the spreadsheet only if I already knew that Cashew’s structure could not represent my needs.
Compared with envelope-style budgeting
Envelope budgeting is useful for people who like assigning money to purposes before spending it. Cashew can support that mindset through expense and budget tracking, but the app should not be mistaken for a physical separation of funds. A number on a screen does not prevent a card payment from going through.
If you need firm behavioral barriers, separate bank accounts, cash envelopes, or card controls may be stronger. Cashew is better as a visibility tool: it shows whether your behavior matches your plan, while the envelope method can make overspending harder in the first place.
Compared with a full financial dashboard
A full dashboard may be the better fit for someone who wants investments, liabilities, net worth, and multiple accounts in one place. Cashew’s appeal is the opposite: it keeps attention on expenses and budgets. That narrower scope is not a weakness for everyone. In fact, people who abandon broad financial platforms because they feel overwhelming may stick with a focused tracker longer.
I would not select it as the only financial tool for a complicated financial life. I would select it when the immediate problem is everyday spending and I want a manageable starting point.
The cost of switching
Changing budgeting apps is rarely difficult because of installation. The real cost is rebuilding categories, learning a new workflow, and deciding which historical information is worth carrying forward. Before moving to Cashew, I would write down my current categories and identify which ones genuinely influence decisions. Recreating a smaller, cleaner structure is often better than importing every old label.
I would also run both systems briefly if accuracy matters. Record new expenses in the new tracker while keeping the old method available for reference, then compare totals at the end of a cycle. This catches differences caused by timing, refunds, transfers, or inconsistent category choices. It is less exciting than immediately deleting the old app, but it prevents a false sense of control.
For someone starting from nothing, Cashew has the easier transition: create a modest structure, enter current spending, and avoid trying to reconstruct an entire financial history on the first day. The goal is a reliable present-day habit, not a perfect archive.
Who should choose it
I recommend Cashew to someone who wants a dedicated place for personal expense tracking, is willing to enter purchases, and prefers a focused budgeting experience over a crowded financial dashboard. It is especially suitable if you learn from seeing your own spending patterns and want to make adjustments during the month rather than waiting for a statement.
I would also consider it for a person who has tried spreadsheets but stopped maintaining them. The simpler, app-based workflow may remove enough friction to make regular reviews realistic. Its Everyone age rating and support for older Android devices also make it approachable for a broad range of users, provided the device meets the stated minimum operating system requirement.
Who should skip it
I would look elsewhere if automatic transaction collection is essential, if I need advanced business accounting, or if my household requires detailed shared-wallet reconciliation. I would also skip it if I dislike manual entry on principle. No amount of attractive organization can compensate for a workflow I will not use.
People who need strong spending restrictions should combine tracking with a method that limits access to money. A tracker can reveal an overspend after it happens; it is not the same as a control that stops the purchase. Likewise, anyone seeking investment analysis or a complete net-worth picture should begin with a broader financial platform and use an expense tracker only if it adds value.
My recommendation after using it
Cashew is worth trying when your biggest money problem is lack of visibility, not lack of financial products. Its focused design, free starting price, and clear use as an expense and budget tracker make it a sensible option for building a daily habit. The strong average rating and sizable user base add reassurance, but my recommendation rests more on the fit between the app and the user’s behavior.
I would install it, create only the categories I can explain, and test the routine for a full spending cycle before considering any optional purchase. If entering expenses feels manageable and the weekly review changes what I do, the app is doing its job. If I keep postponing entries or need automatic account-wide reporting, I would switch to a banking-linked or more specialized alternative instead.
In my view, the best reason to choose Cashew is not that it promises to solve every financial problem. It is that it gives everyday spending a dedicated place where small decisions become visible. For the right user, that modest focus is a strength; for someone seeking automation or complex financial management, it is the boundary that points toward another tool.
Pros
- Clean interface makes daily expense tracking quick and easy.
- Flexible categories help organize spending around personal habits.
- Budget alerts can encourage better control before overspending.
- Recurring transactions reduce the effort of entering regular bills.
- Useful charts provide a clear overview of spending patterns.
Cons
- Some advanced features may require a paid subscription.
- Manual entry can become tedious for users with many transactions.
- Limited bank integration may depend on country and supported institutions.
- Initial setup takes time if you want detailed budgets and categories.
- Users may need to customize defaults for more precise tracking.
FAQs for Cashew—Expense Budget Tracker
What is Cashew—Expense Budget Tracker used for?
Cashew—Expense Budget Tracker is designed to help you record expenses, organize spending by category, monitor income, and understand where your money goes. During use, the app is most helpful for people who want a clearer overview of daily purchases and monthly budgets without relying on complicated spreadsheets. It can support personal finance planning, recurring payments, savings goals, and general spending awareness.
Does Cashew support budgets, recurring expenses, and financial goals?
Yes, Cashew is built around budgeting and expense planning rather than simple transaction notes. You can generally create spending limits for categories or periods, add recurring income and bills, and follow progress toward savings objectives. These tools are useful for identifying overspending before the end of the month. However, the exact options and customization available may depend on the app version and your device platform.
Can I use Cashew without connecting my bank account?
Cashew is suitable for users who prefer manually entering their financial activity instead of giving an app direct access to bank accounts. This approach offers more control over privacy and lets you track cash purchases, shared expenses, and accounts that may not support automatic synchronization. The trade-off is that accurate results depend on remembering to add transactions consistently and keeping balances updated.
Does Cashew protect my financial information and work offline?
Because expense trackers contain sensitive information, privacy and data handling should be checked carefully before entering real financial details. Cashew is primarily intended for recording and organizing the information you provide, but users should review its current privacy policy, permissions, backup features, and synchronization settings. If offline access is supported, you may still need an internet connection for cloud backups or syncing between devices.
Is Cashew—Expense Budget Tracker free to download?
Cashew can be downloaded from the relevant mobile app store, but availability of free features, optional purchases, subscriptions, advertisements, and premium tools may change over time. Before downloading, check the current store listing for pricing and in-app purchase details. It is also worth confirming whether features such as advanced reports, synchronization, export options, or additional customization require payment.

Cashew—Expense Budget Tracker
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via dapperappdeveloper@gmail.com, visit http://cashewapp.web.app/, or review their https://cashewapp.web.app/policy.html.










